The short answer: Most Oregon homeowners policies cover sudden and accidental water damage, such as a burst pipe, a split supply line or a failed water heater. They usually exclude gradual leaks, maintenance problems and flooding from outside, which needs separate flood insurance. Your own policy wording decides, so read it or ask your agent.
What is usually covered
Policies are written around the word “sudden.” Water that escapes all at once, from something that broke, is the classic covered loss.
- A burst or split pipe
- A failed washing machine, dishwasher or refrigerator supply line
- A water heater that ruptures
- Water used by firefighters to put out a fire
- Overflow from a toilet or tub (the damage it causes, not the plumbing repair)
What is usually not covered
Insurers draw the line at damage that happened slowly or that comes from outside the house.
- A slow leak under a sink that’s been dripping for months
- Damage from lack of maintenance, like a roof that’s past its life
- Flooding from rising surface water, which needs a separate flood policy
- Sewer or drain backup, unless you’ve added that endorsement
- Freeze damage in a home left unheated or vacant, depending on the policy
How to keep a claim moving
Stop the damage first. Your policy expects you to prevent things getting worse, and an insurer can push back on damage that grew because nobody acted.
Document everything with photos before anything gets thrown away. Keep receipts. And make sure the scope of work is written the way your insurer prices it. We write ours in Xactimate, the program most adjusters use, so the numbers line up instead of turning into a week of emails.
Mitigation and repair are often separate
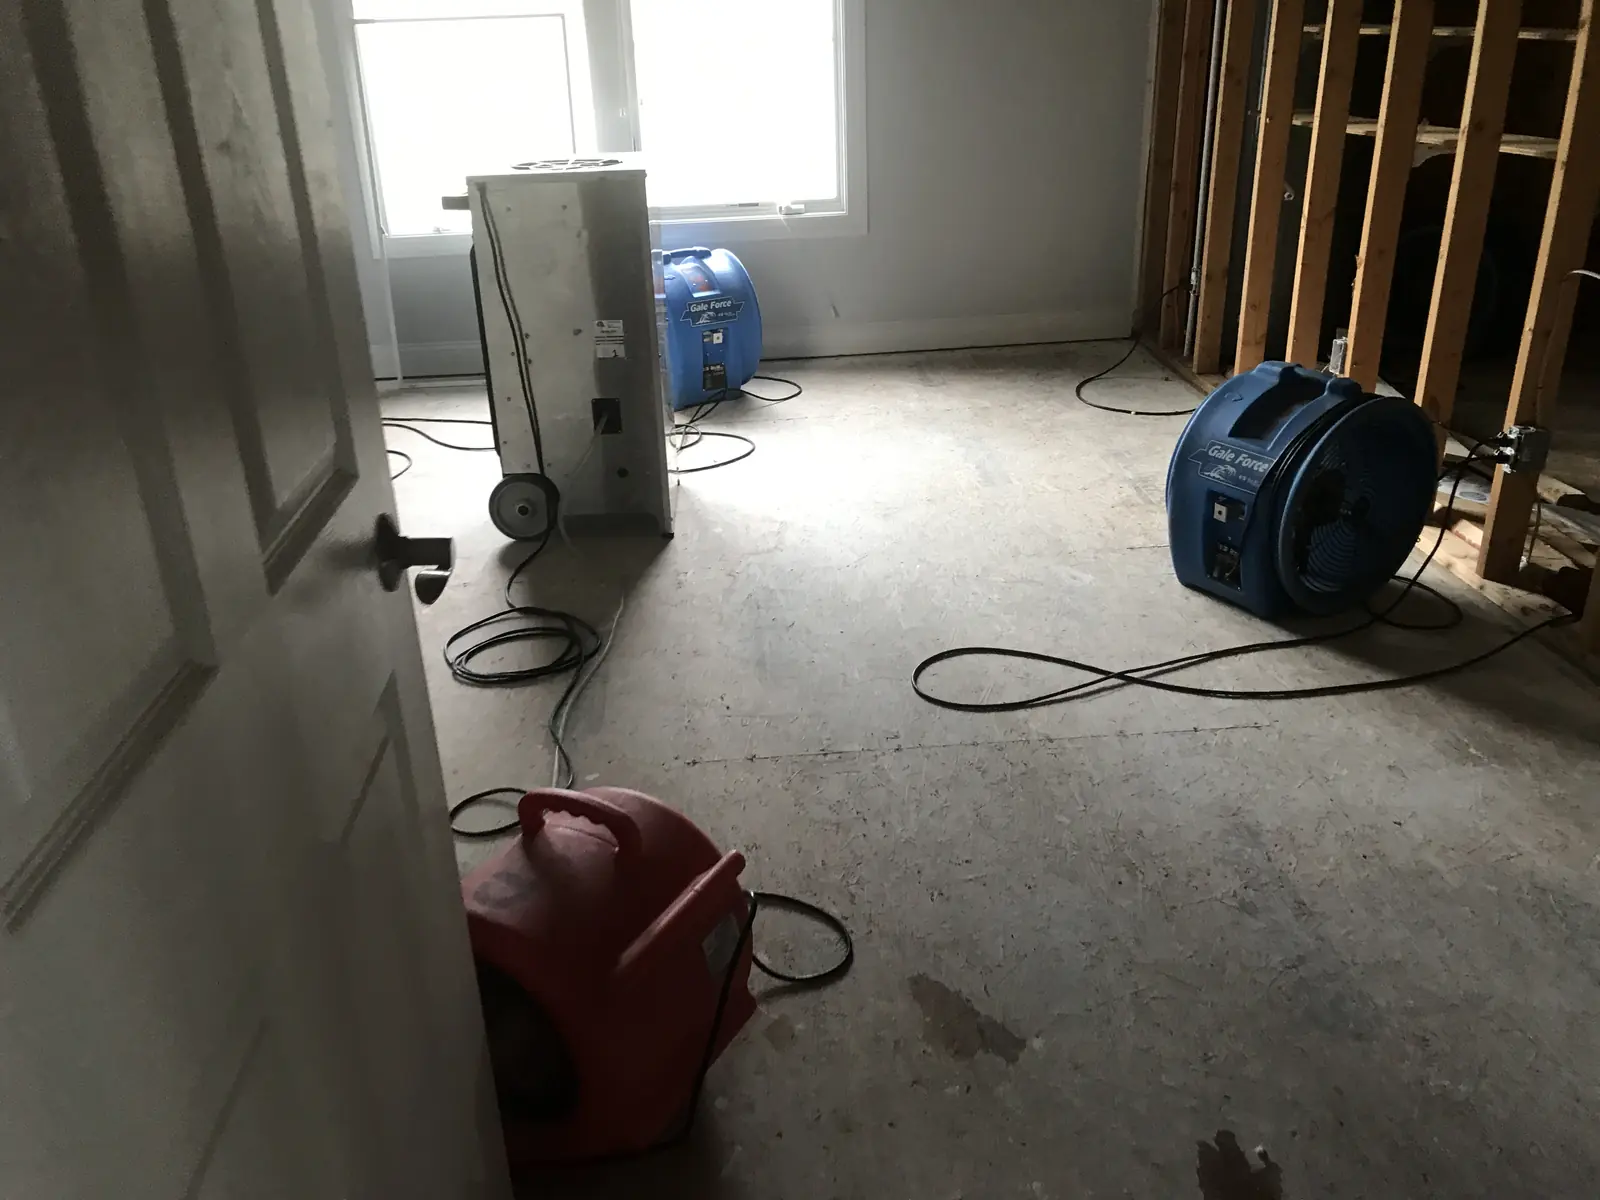
The emergency work (extraction, tear-out, drying) is called mitigation. Putting the house back is the repair. Insurers often handle them as two stages, and the adjuster may want to see the dried-out structure before approving the rebuild. That’s normal, not a sign anything is wrong.
Can you pick your own contractor?
Yes. Your insurer may recommend a company, but you can choose who works in your home. If you’re not sure how your policy handles it, ask your adjuster. We’re happy to talk to them directly.
One more thing: your deductible is yours to pay, whoever does the work. Be wary of anyone who offers to “waive” it. That’s a problem for you, not a favor.
Need help now? Call 541-797-4233, any hour, or read about our insurance claims & billing service in Bend.